

Equipment Finance Broker Sydney
Financing equipment for your business usually means comparing a handful of loan structures, and working out which one actually suits your situation. LendWise is an equipment finance broker Sydney businesses can speak with to compare options across our lender panel, understand the costs involved, and get support from your first enquiry through to funding.
Equipment Finance Built Around Your Business
Financing equipment usually means comparing a handful of loan structures, and it’s not always clear which one actually suits your business. At LendWise, we broker equipment finance across Sydney, comparing lenders on our panel so the loan fits the equipment you’re financing and how your business will use it. Whether it’s a work vehicle, machinery, tools, or technology, new or used, we look at your full situation first.
Equipment finance isn’t the same for every business. The right structure depends on whether you’re buying new or used, and how long you’ll actually use the equipment. It also depends on whether you want to own it outright or lease it instead. We work through that with you first, then match it to a lender on our panel.
Equipment Finance Options for Different Situations
Not every equipment purchase calls for the same finance structure. The right option depends on what you’re buying, how long you’ll use it, whether you want to own it at the end, and how it fits against your other business costs.
Chattel Mortgage
A chattel mortgage means your business owns the equipment from day one. The lender takes a mortgage over the asset as security, and you repay the loan over an agreed term. For businesses registered for GST, it may allow the GST on the purchase price to be claimed upfront rather than spread across the loan. It suits businesses that want full ownership from the start and plan to keep the equipment long term.
Finance Lease
With a finance lease, the lender owns the equipment and you make lease payments over an agreed period. At the end of the term, you typically have the option to purchase the equipment for its residual value, extend the lease, or return it. It suits businesses that want to preserve cash flow upfront and don’t need ownership during the lease term.
Hire Purchase
A hire purchase agreement means you use the equipment while making instalments over a set term. Ownership transfers to your business once the final payment is made. It works similarly to a chattel mortgage in practice, but the ownership timing differs. It suits businesses that want a fixed repayment schedule and are happy to take ownership at the end rather than from the start.
Operating Lease
An operating lease is closer to a rental arrangement. You use the equipment for an agreed period, and the lender retains ownership throughout. At the end, you return the equipment rather than buying it. It suits businesses that use equipment for shorter periods, upgrade regularly, or don’t want the asset sitting on their books.
Equipment Rental
Equipment rental is a short-term arrangement where you pay to use the equipment for days, weeks, or months without any finance commitment. There’s no loan, no residual, and no ownership at the end. It suits one-off jobs or seasonal work where buying or leasing doesn’t make financial sense.
Why Equipment Loans Matter
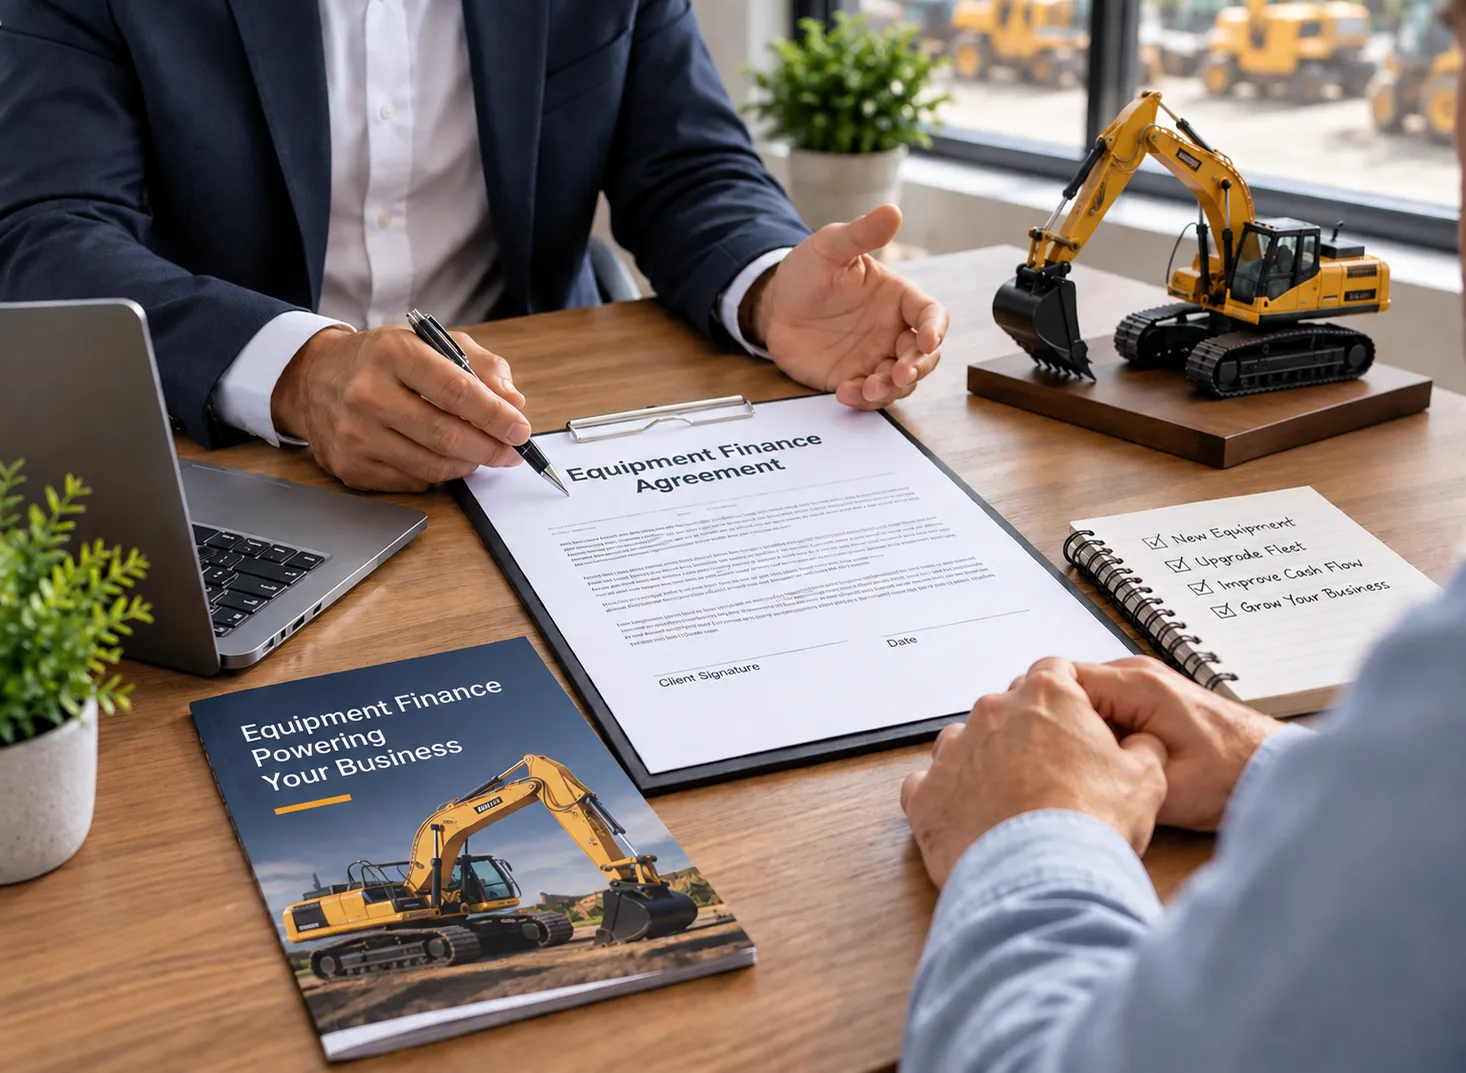
Equipment finance isn’t one structure. A chattel mortgage, a finance lease, and a hire purchase agreement all work differently. The right one depends on how long you’ll use the equipment, how you want to handle ownership, and how the loan sits against your other business costs.
A supplier’s job is to sell you the equipment. Getting you the right loan structure sits well down their list of priorities. Our job is the loan itself. What your business can afford, what you’re trying to achieve, and which lender on our panel suits your situation.
For Sydney businesses, that also means factoring in registration, insurance, and running costs. These sit alongside the loan repayment, on top of the price of the equipment itself.
Our Lender Panel
We compare finance options across our lender panel to find the right fit for your situation.
What Do Lenders Look At for Equipment Finance?
Equipment finance assessments are different from home loan or car loan assessments. Lenders look at your business, the asset you’re financing, and how the two fit together.
Our Process
Here’s what working with an equipment finance broker actually looks like. It runs from your first message to the day it’s funded.

Submit Your Enquiry
Discuss Your Options
Application & Approval
Receive Your Funds
Equipment Finance Across Sydney
LendWise arranges equipment finance for businesses across western Sydney, including Parramatta, Penrith, Marsden Park, and the surrounding suburbs. Whether you’re financing a work vehicle, machinery, tools, or technology, lender appetite can vary depending on the asset type and your business profile. Having a broker who knows which lenders fit which situations saves you from applying in the wrong place.
Wherever your business is based, the process stays the same. You get the same lender panel, the same point of contact, and the same support from your first enquiry through to funding.
Why Choose LendWise as Your Home Loan Broker
Here’s what you get when you work with LendWise.
Real home loan options
One Broker From Start to Finish
Your Best Interests Come First
No Direct Broker Fee
Support After Settlement
Access to Multiple Lenders
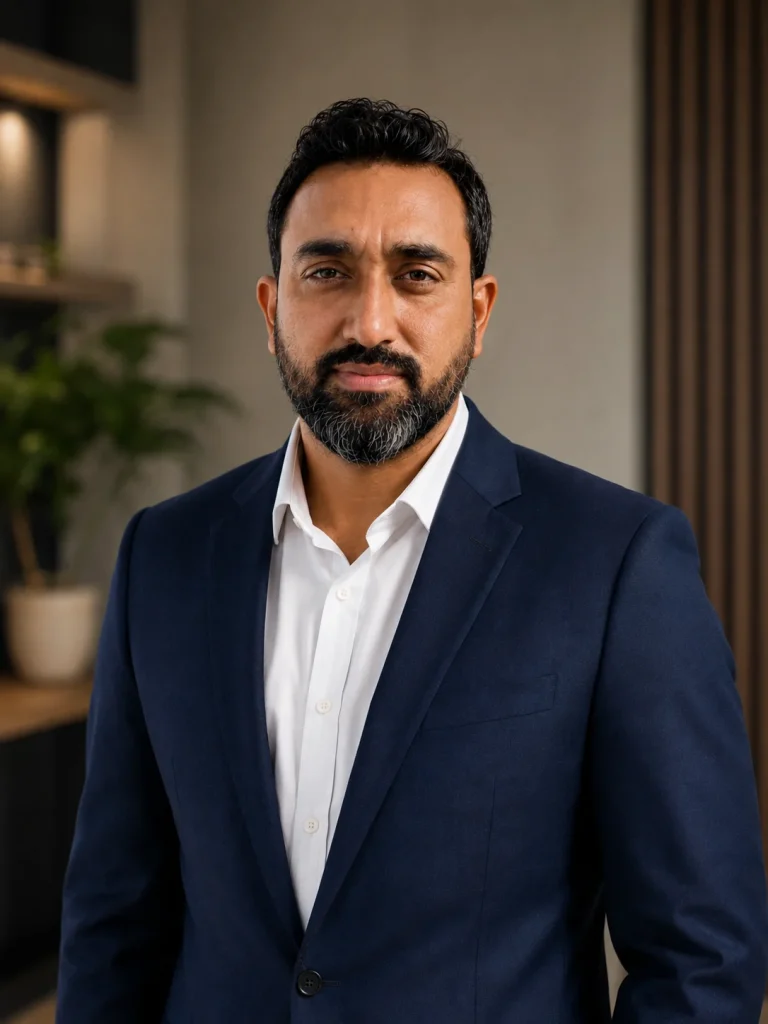
Rajeev Vij
FOUNDER - MORTGAGE & FINANCE BROKER
Your Equipment Finance Broker, Personally Guiding You
I’m Rajeev Vij, founder and mortgage and finance broker at LendWise. I work with business owners across Sydney to understand their equipment finance needs and find a loan structure that fits how the business actually runs, rather than defaulting to whatever a supplier or bank offers first.
I’m a FBAA member and hold a Certificate III in Mortgage Broking and a Diploma in Finance and Mortgage Broking. I have more than two years of experience in the mortgage and finance industry.
From your first enquiry through to funding, I’ll be your main point of contact. I’ll help you understand your options, deal with the lender directly, and keep you informed as your application progresses.
Talk to a Equipment Finance Broker in Sydney
Financing equipment for your business doesn’t have to be a guessing game. We can help you compare lenders across our panel and find a loan structure that fits your business and the asset you’re financing.
Speak with Rajeev Vij at LendWise to discuss your car loan options.
Frequently Asked Questions
What is equipment finance?
Equipment finance is a loan or lease used to buy business equipment, machinery, or vehicles. It saves you paying for it outright. It's usually set up as a chattel mortgage, a finance lease, or a hire purchase. Each one works differently. The equipment itself is often used as security for the loan.
What's the difference between a chattel mortgage and a finance lease?
A chattel mortgage means you own the equipment from the start. You repay the lender over the loan term. A finance lease works differently. The lender owns the equipment, and you make lease payments for an agreed period, often with the option to buy it at the end. Which one suits you depends on how you want to handle ownership, and how your business claims the asset.
Can equipment finance cover a work vehicle or truck?
Yes. Equipment finance covers work vehicles and trucks, as well as machinery, tools, and technology. We look at the same panel of lenders, regardless of what you're financing. Then we match the structure to how you'll use it.
Do I need a deposit for equipment finance?
It depends on the lender and the equipment you're financing. Some loans are available with no deposit. Others need one. This is more common for older or higher-value equipment. We'll talk through what makes sense once we understand your situation.
Can I finance used or second-hand equipment?
Yes. Lenders on our panel finance both new and used equipment. The age and condition can affect which lenders will finance it, and on what terms. We factor that in when comparing your options.
What documents do I need to apply?
Usually proof of identity and business details. We'll also need information about the equipment you're financing. If you're a sole trader, or a newer business, we might need a bit more. We'll let you know once we understand your situation.
How does equipment finance affect GST and tax?
The structure you choose can affect how you handle GST and depreciation. We can talk you through the general differences. But the specifics for your business are worth checking with your accountant before you decide.
How long does equipment finance approval usually take?
It depends on the lender, the type of equipment, and how quickly your documents come through. Some approvals come back quickly. Others take longer, if a lender needs more information. We'll give you a realistic timeframe once we know which lender fits your situation.
Our Insights