

Home Loan Broker Sydney
Buying a home in Sydney can feel complicated, especially when you’re comparing lenders, working out your borrowing capacity and trying to understand which loan is right for you. LendWise is a home loan broker Sydney borrowers can speak with for straightforward guidance, suitable loan options and support from pre-approval through to settlement.
Home Loans for Sydney Buyers
Whether you’re buying your first home, moving to a new property, refinancing an existing loan or purchasing an investment property, LendWise can help you understand your home loan options in Sydney.
Your income, expenses, deposit, existing debts and property plans all affect which loans you may qualify for. We take the time to understand your circumstances and can help you compare suitable options, assess your borrowing position and work through the application process.
For eligible first home buyers, this can also include understanding low-deposit options and Australian Government home buyer schemes that may help you enter the property market with a smaller deposit.
Home Loan Broker for Different Borrowing Needs
The right home loan depends on more than the property you’re looking to buy. Your deposit, income, existing commitments and plans for the property can all influence which loan options may be suitable. LendWise can help you understand the options available for your circumstances and compare suitable loan products before you apply.
First Home Buyers
Buying your first home comes with questions about deposits, borrowing capacity, government schemes and loan repayments. We can help you understand your options, work out what you may be able to borrow and prepare for the home loan application process.
Home Buyers
If you’re buying a home in Sydney, comparing loan features and lender requirements can help you make a more informed decision. We can help you assess suitable home loan options based on your financial position and property plans.
Refinancing
If you already have a home loan, refinancing may be worth considering if your current rate, loan features or circumstances have changed. We can help you compare refinancing options and understand the potential costs and benefits before switching lenders.
Low Deposit Home Loans
A 20% deposit isn’t the only way to buy a home. Some borrowers may qualify for lending with a smaller deposit, although lender requirements and costs can vary. Eligible first home buyers may also have access to government schemes designed to reduce the deposit required.
Investment Loans
Buying an investment property requires a different approach to assessing finance. We can help investors understand available loan options, borrowing requirements and loan structures based on their investment plans.
Self-Employed Borrowers
If you’re self-employed, your income may be assessed differently from someone receiving a regular salary. We can help you understand what lenders may require and explore home loan options based on your financial circumstances.

Home Loan Broker vs Going Direct to a Bank
When you go to a bank, you only see what that bank offers. A broker compares options from a panel of lenders across the market to find what fits your situation. Banks work for the bank. As a broker, we’re bound by the Best Interests Duty, meaning every recommendation is based on what suits you, not what pays us more.
There’s generally no direct fee to you either, as the lender pays us when your loan settles. We also handle your application from enquiry through to settlement, and stay in touch after your loan is in place to help if your situation changes.
The Benefits of Using a Home Loan Broker in Sydney
Choosing a home loan isn’t just about the lowest rate. Lenders have different policies, fees and features, so the right loan depends on your circumstances. LendWise helps you compare suitable home loan options, understand your borrowing position and navigate the application process.
Our Process
We help with a wide range of home loan situations across Sydney. Here’s what the process actually looks like.

Submit Your Enquiry
Discuss Your Options
Application & Approval
Receive Your Funds
Our Lender Panel
We compare finance options across our lender panel to find the right fit for your situation.
Government Home Buyer Schemes for Sydney Buyers
Government scheme eligibility, price caps and requirements can change. Check the current Government rules and participating lender requirements before making a purchase.

Why Choose LendWise as Your Home Loan Broker
Here’s what you get when you work with LendWise.
Real Home Loan Options
One Broker From Start to Finish
Your Best Interests Come First
No Direct Broker Fee
Support After Settlement
Access to Multiple Lenders
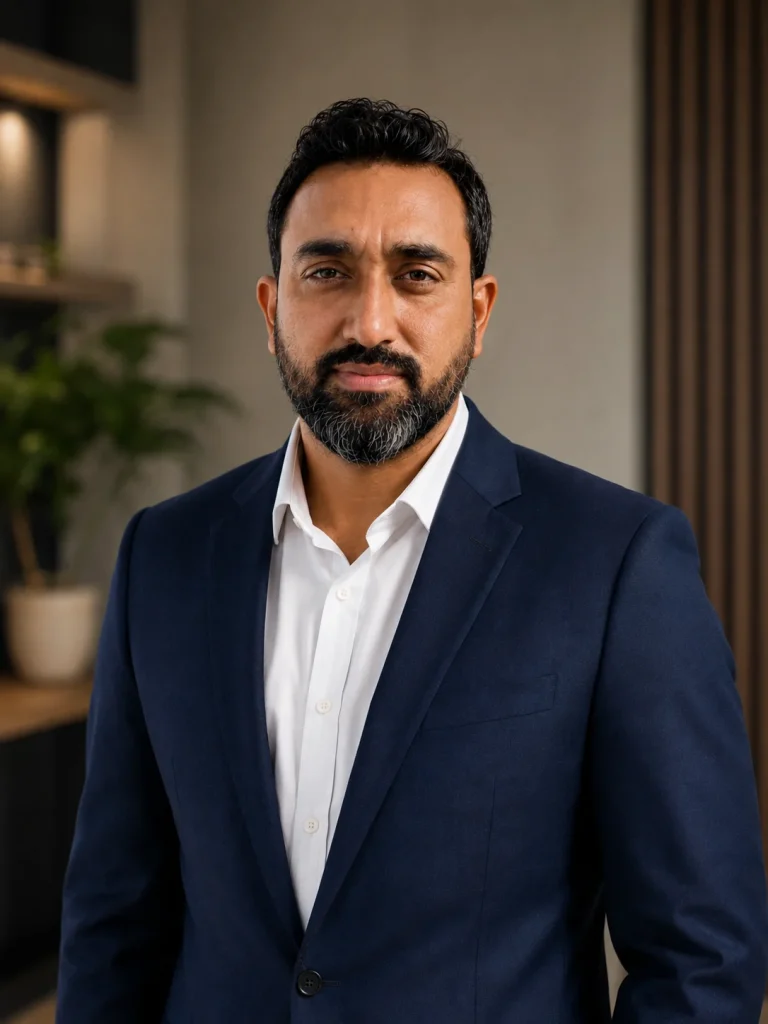
Rajeev Vij
FOUNDER - MORTGAGE & FINANCE BROKER
Your Home Loan Broker, Personally Guiding You
I’m Rajeev Vij, founder and mortgage and finance broker at LendWise. I work with business owners, property investors and other borrowers to help them understand their commercial finance options and navigate the loan process.
I’m a FBAA member and hold a Certificate III in Mortgage Broking and a Diploma in Finance and Mortgage Broking. I have more than two years of experience in the mortgage and finance industry.
From your first enquiry through to settlement, I’ll be your main point of contact. I’ll help you understand your options, communicate with the lender and keep you informed as your application progresses.
Talk to a Home Loan Broker in Sydney
Working out which home loan fits your situation doesn’t have to be a guessing game. We can help you compare lenders across our panel and find a loan that works for your property goals.
Speak with Rajeev Vij at LendWise to discuss your home loan options.
Questions About Working With a Home Loan Broker
What is a Home Loan?
A home loan is money you borrow from a lender to buy a property, which you repay over an agreed term with interest. The property is generally used as security for the loan. Home loan terms are commonly up to 30 years, although the appropriate term depends on your circumstances and lender.
What does a home loan broker do?
A home loan broker helps you understand your borrowing position, compare suitable loan options from participating lenders and manage the application process through to settlement. We look at your circumstances, explain the costs and features of the options available, and help you understand why a particular loan may be suitable.
Is it better to use a home loan broker or go directly to a bank?
It depends on your circumstances and what you want from the process. A bank can generally offer its own home loan products, while a mortgage broker can compare loans from a panel of lenders. A broker can also help explain loan costs, features and lender requirements and manage the application through to settlement.
How much does a mortgage broker cost?
In many cases, the lender pays the mortgage broker a commission after the loan settles, so you don't pay the broker directly. However, some brokers may charge a fee in certain circumstances. We will tell you upfront if a fee applies to your situation.
How much deposit do I need to buy a home in Sydney?
A 20% deposit is a common benchmark and can help you avoid Lenders Mortgage Insurance (LMI), though smaller deposits are possible. Eligible first home buyers may qualify for the Australian Government 5% Deposit Scheme, and eligible single parents or guardians for as little as 2%. Help to Buy is a separate 2% deposit pathway, but you can't combine it with the 5% Deposit Scheme on the same purchase.
What is the Help to Buy Scheme?
Help to Buy is an Australian Government shared-equity scheme that allows eligible buyers to purchase a home with a minimum 2% deposit, while the Government can contribute up to 30% for an existing home or 40% for a newly built home. Income limits, property price caps and other eligibility requirements apply. For NSW capital city and designated regional centres, the current property price cap is $1.3 million.
How much can I borrow for a home in Sydney?
Your borrowing capacity depends on factors such as your income, living expenses, existing debts, deposit, loan term and the lender's assessment criteria. Different lenders can assess the same borrower differently, so an online calculator can only provide an estimate. We can help you understand your borrowing position based on your actual circumstances.
Can I get a home loan if a bank has already declined my application?
Possibly. A decline from one lender doesn't automatically mean you cannot get a home loan, because lenders have different credit policies and assessment criteria. However, applying with another lender isn't guaranteed to result in approval. We can help you understand why the application was declined and whether there may be other suitable options.
Does your support continue after my home loan settles?
Yes. We stay in touch after settlement and can help you review your home loan as your circumstances change. If you later consider refinancing, changing your loan structure or buying another property, we can discuss your options with you.
